A collections policy defines the timing, tone, ownership, evidence and escalation used when customer balances become due or overdue.
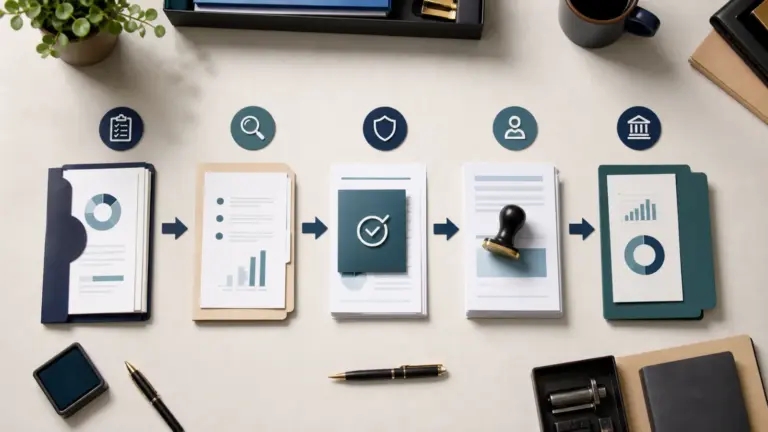
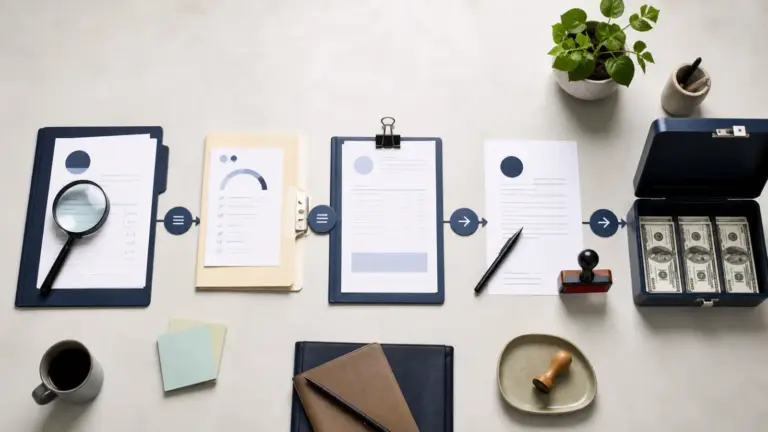
Set a sequence from pre-due reminder through personal contact, payment plan, service hold and external collection, with legal review where needed.
Small-business collection policy timeline
| Timing | Action | Owner |
|---|---|---|
| 3 days before due | Confirm delivery and send a friendly reminder | Billing |
| 1 day past due | Send current balance and easy contact path | Billing |
| 7 days past due | Personal contact, record reason and payment promise | Account owner |
| 15 days past due | Manager review of dispute, credit, open work, and payment plan | Finance manager |
| 30+ days past due | Formal notice and legal review before hold or collection agency | Authorized manager |
Collection efforts should be consistent while allowing evidence-based exceptions. Record every contact, promise, dispute, and returned payment. Debt collection rules differ by jurisdiction and customer type, so the final escalation and collection-agency language needs local review.
Use a consistent process with room for exceptions
Assign each stage to a role and define when a dispute, hardship request or broken promise changes the route. Keep communication factual: reference the invoice, agreed due date, amount outstanding and available next step. Local collection rules and contract terms can constrain fees or escalation. Have those checked before adding them to a standard sequence.
Example
The policy sends a reminder three days before due, follows up at 1, 7 and 15 days past due, and requires manager review before any service suspension.
What to watch for
Debt collection rules vary by jurisdiction and customer type, so aggressive templates and automatic fees can create legal and reputational risk.
Put the next step into practice
Read our guide to credits, refunds and debit notes for the related workflow. Explore Invoice Crowd customer invoicing to see the product capabilities relevant to your setup.