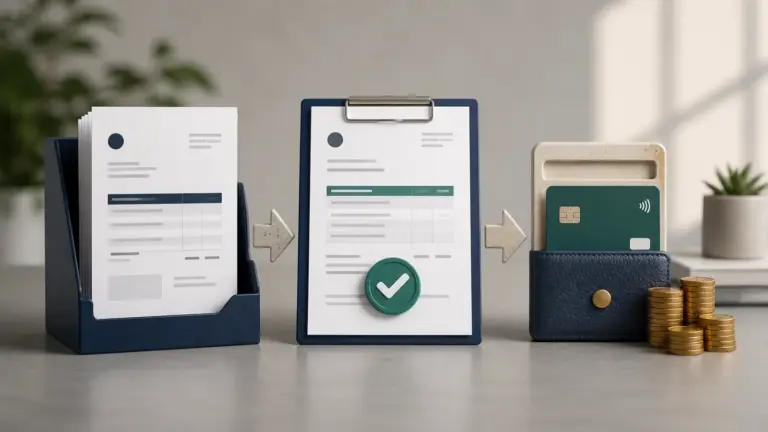
Credit control is the policy and operating process used to decide who receives credit, on what terms, to what limit and how overdue balances are handled.
Combine credit checks, limits, payment terms, monitoring and graduated collection actions that match customer risk and business capacity.
Credit control process and escalation ladder
| Moment | Credit-control action |
|---|---|
| Before sale | Credit application, identity, references, credit report where appropriate, limit and terms |
| Before due | Verify invoice delivery and send a helpful reminder |
| 1-7 days late | Contact the customer, identify dispute or processing issues, and secure a payment promise |
| 8-30 days late | Escalate ownership, review open orders and credit limit, and document a payment plan if justified |
| Serious delinquency | Manager and legal review before service hold, external collection, or write-off |
Effective credit control balances sales and credit risk. Clear credit terms, timely invoices, evidence, and consistent follow-up are usually more important than a harsh final letter. Local debt collection and late-fee rules still apply.
Make escalation predictable for customers and staff
Agree who may extend terms, approve a payment plan or place new orders on hold. A reminder sequence should reflect the account history and dispute status rather than send the same message indefinitely. Track promises to pay and check them on the agreed date. Escalation works better when the customer already knows the terms and the next step.
Example
A new customer receives a $5,000 limit and Net 15 terms, which are reviewed after three on-time payments.
What to watch for
Sales volume without collectible cash can weaken working capital, but overly rigid control can reject good customers and slow growth.
Put the next step into practice
Read our guide to credits, refunds and debit notes for the related workflow. Explore Invoice Crowd customer invoicing to see the product capabilities relevant to your setup.